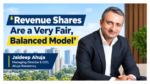
‘Revenue Shares Are a Very Fair, Balanced Model’: Jaideep Ahuja, Managing Director & CEO, Ahuja Residency
Ahuja Residency is expanding in Uttar Pradesh, with a 37-room boutique property opening in Greater Noida, a 150-room hotel due by 2030, and a 60-room boutique property in Haridwar. In a conversation with Palash Roy, Founder & Editor, Realty & More, Jaideep Ahuja, Managing Director & CEO, Ahuja Residency, talks about how the group picks a brand for each property, the three models open to hotel owners, demand in spiritual and tier 2 and 3 cities, the service apartment opportunity, and why any capital the group raises “has to be patient capital”.
Palash Roy: First of all, tell us about your expansion plans. You are getting into UP, or expanding more into UP. Tell us more about that.
Jaideep Ahuja: Well, we are expanding everywhere. We have a lot of belief that there is a lot of scope in UP. We are opening a 37-room boutique property next month in Greater Noida. We have a larger 150-room property also signed up, where construction has just started, and we expect it to be ready by 2030. In addition, we are also opening a 60-room boutique property in Haridwar, which will open in November of this year.
Now you have five different brands. How do you choose? What is the rationale behind deciding that a property will come up under a particular brand?
Some of it is easy. Yuhi is a predominantly Japanese brand, so wherever there is a significant Japanese presence, we will look at doing a Yuhi there.
A lot of it also gets decided by what’s available. AR Suites is an apartment hotel brand, or an all-suites brand. So if developers are building all-suites properties or apartments, those can easily be converted into AR Suites.
For us, one of the most exciting brands is aiR, which is a boutique brand. Cities where air quality is a big issue, which is now across North India, are great candidates for aiR properties. I recently read that maybe Mumbai is the third most polluted city in the world, so the issue is spreading across India.
So is aiR predominantly a B&B?
No, aiR is our equivalent of a four-star brand. It has many unique selling propositions. One of them is that it delivers the best air quality you can get. We keep AQI levels below 50, mostly below 10. Beyond that, there is technology and there are design aspects. It’s our top-end brand.
When a property owner looks at tying up with a hospitality brand, what should they opt for? How should they approach a hospitality brand?
If you’re a property owner, you predominantly have three models for working with a hospitality brand: the traditional management contract, a revenue-sharing arrangement, or a lease deed. All have their own pros and cons.
The lease deed is for the most risk-averse landlords. You get a fixed rental and no share in the upside. But if the property doesn’t do well, that’s not your problem. This works well for smaller properties.
On the other hand, under a management contract you end up paying 6–10% of revenues to a management company, and all expenses are on the owner’s account. So it is the riskiest for owners. But if you have a lot of confidence in your location and property, this is where you can get the best returns, because over 90% of the revenues come to you. If revenues are good, you make the most money. But if you have events like COVID, when hotels have to shut down, it is also the riskiest, because you get no rentals and all manpower and maintenance expenses are on your head.
For larger properties, the larger chains will only do management contracts. So if you own a hotel with 200-plus rooms, you have no choice except a management contract.
In between these two is the revenue share model, where the owner and operator share revenues and the operator bears the expenses. As an owner, you don’t carry that risk, because the expenses are not yours. But the fortunes of the operator and the owner are tied together, and both work to increase revenues because that is what they are splitting.
I believe revenue shares are a very fair, balanced kind of model, and I think this is what will gain popularity. In fact, a lot of the larger brands that would do nothing except management contracts are now being forced to do revenue shares. I think this will continue.
You have announced your foray into Haridwar. Do you plan to go to more spiritual cities and temple cities, like Ayodhya or Shirdi?
Yes, we do. We believe these spiritual cities have a dearth of quality, consistent accommodation. We’d love to create a brand that covers them, so that whether you are going to Ayodhya, Haridwar, Banaras or Balaji, you know an Ahuja Residency brand is available there. Haridwar is the first of many, I hope.
What are your expansion plans in tier 2 and tier 3 cities, and how do you choose which brand goes to which city?
The problem a lot of owners have is what I call this: they don’t look at return on investment, they look at return on ego. They put luxury brands in places that don’t need those brands.
We’ve seen some of our greatest success come from tier 3 towns and industrial zones that have been very underserved by good hospitality. For me, the location within a particular city is what matters most.
I see growth in India’s metros. Delhi and Bombay are doing high occupancies and high ARRs, and tier 1 cities like Pune, Hyderabad and Bangalore are all doing extremely well. But even in tier 2 cities such as Indore and Kanpur, there is a lot of scope. Then there are industrial zones: Dholera is coming up. We have two running Yuhi hotels in Sri City in Andhra Pradesh, on the Andhra–Tamil Nadu border, and we are now building a third hotel there because demand is high.
There are pockets like this, especially in western and southern India, where a lot of new manufacturing is coming up. Toyota is setting up a new plant in Aurangabad, and JSW is setting up a plant. We see demand there and will look at entering those markets.
Which five cities do you think will see the most hospitality demand?
You have to look at two things. In a lot of cities demand is very high, but there is also a large supply pipeline coming. In Tirupati, for example, twice the current supply is in the pipeline. So while demand is definitely going up there, would I want to put up another hotel there? Probably not.
Udaipur and Rishikesh are two of the highest-ARR markets in the country today, but supply is also growing there. So it is very difficult to give you five off the top of my head.
But Mumbai, for sure. Lots of areas are underserved there. Real estate prices are so high that it is difficult to make a hotel viable, but areas like BKC have huge demand. Hyderabad has huge demand too.
I think the western and southern states are currently growing the fastest. For us, that means Chennai and Bangalore. I have a lot of hope that you will now see a lot of demand in Vizag, with the Google data centres and Nippon Steel setting up plants. Where you have very investor-friendly chief ministers like Chandrababu Naidu, you will see a lot of manufacturing going in, and from that you will get hospitality demand.
Service apartments as a category are not very penetrated in our country. How much growth do you see in this segment?
I see a lot of growth in this segment. I was looking at some numbers: service apartments are about a $45 billion business globally, and in India about $1.6 billion in 2024, which were the latest stats. So we are a very, very small part of overall demand.
But as India grows as a manufacturing location, as services keep growing and as we attract foreign capital, expats will follow. When expats come into the country, they need fully serviced apartments. It is still relatively new; not many people know about it and not many brands are present. Marriott Executive Apartments has a few properties and Oakwood has a few properties, but beyond that I don’t see more in the organised sector.
It is really tied to the growth of the Indian economy. If we keep growing at 7–8%, remain the fastest-growing large economy in the world and keep attracting foreign direct investment, that has a direct impact on the service apartment business.
One segment that is slowly gaining traction, with quite good growth, is branded residences. Do you plan to get into that?
I have been observing it very closely, and I am seeing a lot of brands doing it now. I see Western Residences coming up. Near my house, Trident Residences has come up with the Oberois. Everyone is doing it. I think this is hotels capitalising on their brand names. I see Ritz-Carlton doing it globally.
We are not there yet, so it is not something we would do now. Maybe five years plus; it is not on our immediate horizon. It is a very attractive space, but not for us currently. It is more for luxury players whose brand denotes luxury. You want to stay in Ritz-Carlton apartments or Western apartments because these are luxury players.
Even without these brands, uber luxury is gaining a lot of traction, and mass housing has taken a back seat. Do you plan to get into that?
We are not developers, so we won’t be doing that. I have also been seeing that the percentage of affordable housing is falling, and 1.5 crores plus is what is selling.
What we are interested in is maybe using our facility management business to manage condominiums and societies. I think what DLF has shown with Camellias, Aralias and Magnolias is that if you manage societies well, there is huge upside in capital value and in rentals. So I think people will look for excellent hospitality players to manage their properties, and that is something we would be very happy to do.
You are in aggressive expansion mode now. Do you plan to tap the stock markets to raise funds?
We will raise some external capital in the next three years or so. I don’t know yet what that will be. It could be an IPO, or it could be private equity or family office money.
To be honest, I am a little scared of private equity money, because they expect very fast returns. We can definitely scale up, but hospitality is not the easiest business to scale while maintaining quality. We have seen enough examples in our country of hospitality brands trying to scale very quickly and completely losing their way, losing all standards and quality, just to show the number of rooms sold. We don’t want to fall into that trap. So whatever capital we raise has to be patient capital.
Lastly, among all your brands, which is the easiest to run and which is the most challenging?
You’re asking me to choose between my babies! I wouldn’t say anything is challenging. Perhaps our service apartments are the easiest to manage, because our typical length of stay there is over two years. There we provide just fully furnished apartments with housekeeping and maintenance.
The hotels are far more operations-intensive, because there are daily check-ins and check-outs, multiple F&B outlets and laundry. There are lots of other services you need to provide besides housekeeping and maintenance. So in that way the apartments are a little easier and the hotels a little more challenging, but we love them both.